


Harley-Davidson financing works like any secured vehicle loan: you put money down, borrow the rest, and repay it over a fixed term at a fixed rate, with the motorcycle as collateral. Your rate is set mostly by your credit profile, the loan term, and whether the bike is new or used. At the dealership you can finance through Harley-Davidson Financial Services or one of the other lenders we work with, including local credit unions and powersports-specific banks. You can also go through your own bank or credit union, or compare both. The single most useful thing you can do is get pre-approved before you shop, because it turns an emotional decision into a numbers decision.
Here is how the whole thing actually works, without the jargon.
The four numbers that decide your payment
Every motorcycle loan comes down to four variables. Change any one and the payment moves.
- Amount financed. The price, plus tax, title, and fees, minus your down payment and any trade equity.
- APR. Your annual percentage rate. Driven primarily by credit profile, plus term length and new versus used.
- Term. How many months you are paying. Longer term means a lower payment and more total interest paid.
- Down payment. Cash and trade equity applied up front.
The tradeoff people miss is between term and total cost. Stretching a loan out lowers the monthly number and raises what the bike costs you in the end. There is nothing wrong with a longer term if you need the payment to work, but go in knowing what you are choosing.
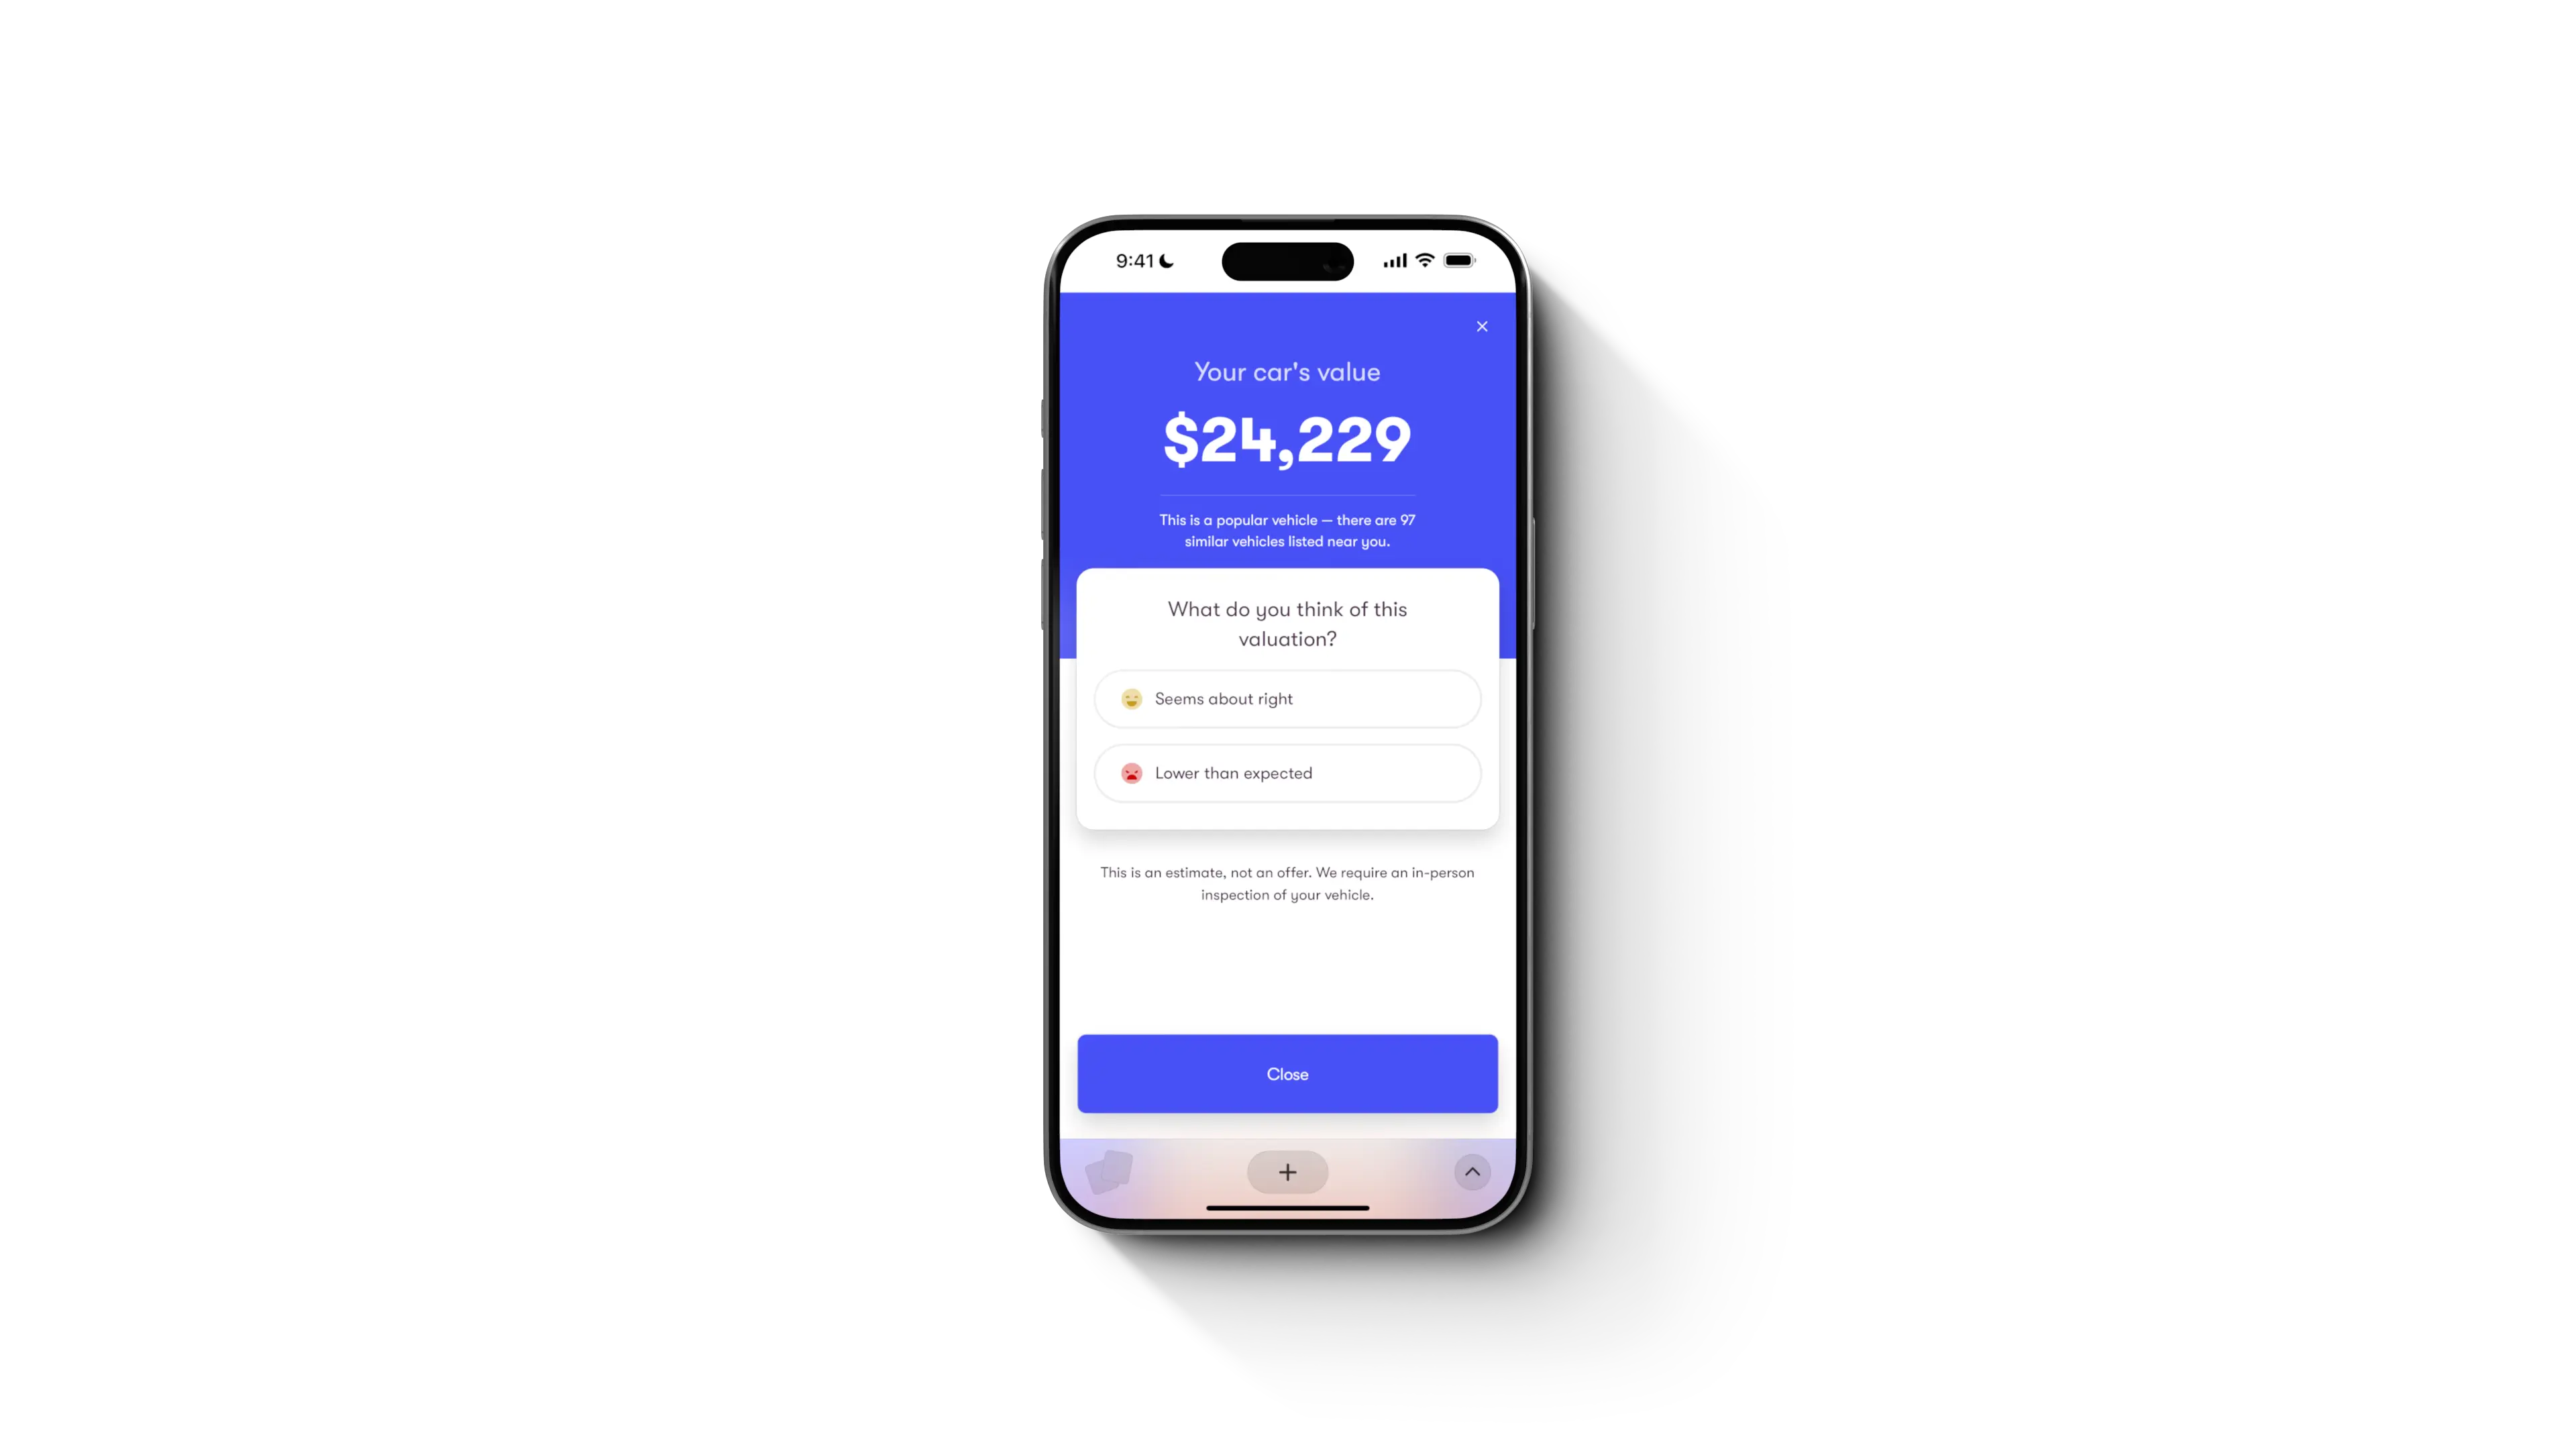
What's your bike worth?
Get an estimate of your bike's trade-in value, based on real local market data — in under 30 seconds.
Powered by
What lenders look at
For a motorcycle loan, the lender is evaluating:
- Credit score and history. The biggest single factor in your rate. We cover this in detail in what credit score you need to buy a Harley.
- Debt-to-income ratio. How much of your monthly income already goes to obligations.
- Income and employment stability.
- Down payment. More down means less risk to the lender, and often a better rate.
- The bike itself. It is the collateral. Newer units generally finance at better rates and longer terms than older ones.
Worth understanding: a motorcycle is a recreational purchase, not transportation, in most lenders' models. Motorcycle loan rates are typically a bit higher than auto loan rates for the same borrower, for that reason. That is normal, not a red flag.
Financing through the dealership vs. your own bank
Both are legitimate. The honest comparison:
| Through the dealership | Your own bank or credit union | |
|---|---|---|
| Convenience | One stop, one signing | Separate application before you shop |
| Lender options | Multiple lenders shopped at once | One lender |
| Promotional rates | Manufacturer promotions available on new units | Not available |
| Relationship pricing | Not applicable | Credit unions often offer member rates |
| Negotiating position | Strong if you already have an offer in hand | Gives you a benchmark |
The best move is to do both. Get pre-approved at your credit union, then let the dealership try to beat it. You lose nothing, and you find out quickly which is actually cheaper. A dealership that cannot beat your rate will tell you so, and a dealership that can just saved you money.
Harley-Davidson also runs limited-time promotional financing, usually on select new models, so a new bike can sometimes cost less to finance than a used one despite the higher price. These offers change often and end on fixed dates, so check Harley-Davidson's current offers or ask our finance office what is running on the bike you want.
What is pre-approval, and why get one?
Pre-approval means a lender has reviewed your information and told you, before you shop, roughly what you qualify for and at what rate.
Three reasons it is worth the twenty minutes:
- You shop with a real budget. Not a guess. Not a monthly payment you hope works out.
- You negotiate from a stronger position. Price and financing become two separate conversations instead of one blended one.
- Surprises happen early, when they are fixable. If there is an error on your credit report, you would much rather find it three weeks before you buy than at the signing table.
You can start the process on our financing page. One thing to know before you click: our online application is a full credit application, which means a hard inquiry on your credit, not a soft-pull pre-qualification. When you fill it out, select the exact motorcycle you are applying for, because your approval is based on the bike just as much as on you. If you want a number in hand without a hard inquiry first, get pre-approved through your bank or credit union, then let us try to beat it.
Does applying hurt your credit?
A pre-qualification that uses a soft credit inquiry does not affect your score. A full application uses a hard inquiry, which can lower your score slightly and temporarily.
Important detail that saves people points: credit scoring models generally treat multiple inquiries for the same type of loan within a short shopping window as a single inquiry. So comparison shopping for a motorcycle loan across a couple of weeks does not stack up damage the way people fear. Spreading applications across several months does.
How much should you put down?
There is no universal rule, but the practical considerations:
- More down usually means a better rate and less total interest.
- More down reduces the chance of being upside down, that is, owing more than the bike is worth. Motorcycles depreciate fastest early, so a small down payment on a long term is the classic way to end up underwater.
- Trade equity counts as down payment. If you have a bike to trade, that equity does the same work as cash. Get a number first: value your trade here.
- Do not drain your reserves. You still need gear, insurance, registration, and the first service. Our guide to what it costs to own a Harley in Louisiana covers those.
Can you lease a Harley-Davidson?
Not with a traditional lease, but Harley-Davidson Financial Services offers H-D Flex Financing, which is structured like a lease while you own the motorcycle. Your monthly payments cover only a portion of the price rather than the full amount, which is what brings the payment down. Terms are 36 or 48 months, and the remaining balance comes due as a balloon payment at the end.
When the term ends, you choose what happens next:
- Pay it off and keep it. Pay the balloon in cash or refinance it.
- Trade it in toward another motorcycle.
- Return it to an authorized Harley-Davidson dealer.
Returning the bike is a real option, but it comes with conditions. According to Harley-Davidson, a return fee, excess wear, mileage, and other charges may apply, and some motorcycles are not eligible for return because of excess wear and tear, heavy modifications, or other conditions. Trading, refinancing, and returning are also subject to dealer acceptance or credit approval.
Flex Financing is available on new motorcycles and some H-D Certified pre-owned models. Program terms change, so ask our finance office for the current Flex terms on the bike you are looking at.
What about extended service plans and gap coverage?
Two products that come up at signing, and both are worth understanding in advance rather than deciding on the spot:
Extended service plan. Coverage beyond the factory warranty. Whether it makes sense depends on how long you will keep the bike, how many miles you ride, and your tolerance for a surprise repair bill. On a modern big twin, a major repair is not cheap.
Gap coverage. Covers the difference between what you owe and what insurance pays if the bike is totaled or stolen. Most relevant if you financed with little down on a long term, which is exactly when a gap is most likely to exist.
Both are typically pro-rated. If you trade, sell, or pay off the bike early, you can usually cancel under the contract terms and get money back for the unused portion. You are not locked into the full amount, which takes some of the pressure off the decision.
Neither is mandatory. Both are easier to evaluate when you are not sitting in the finance office deciding in real time.
Frequently asked questions
What credit score do you need to finance a Harley-Davidson?
There is no single cutoff, and financing exists across a wide range of credit profiles, with the rate changing accordingly. See our full answer.
How long can you finance a motorcycle?
Through Harley-Davidson Financial Services, qualifying buyers can finance a new motorcycle for up to 96 months, and terms up to 84 months are available on used bikes. The term you get depends on the lender, the bike, and your credit approval, and programs can change. Longer terms lower the payment and increase total interest.
Can you finance a used Harley?
Yes. Used-motorcycle financing is widely available, with terms up to 84 months for qualifying buyers, generally at a slightly higher rate than new. Older bikes may have shorter maximum terms. See new vs. used Harley.
Do you need a motorcycle license to finance a motorcycle?
Lenders generally do not require an endorsement to approve financing, and you can purchase a motorcycle without one. You do need one to ride legally. Our Riding Academy is the fastest route in Louisiana.
Can I get financing with bad credit?
Often yes, at a higher rate and typically with a larger down payment. It is worth having the conversation rather than assuming the answer is no. Many people who assume they will not qualify do.
Should I finance through the dealer or my bank?
Get a pre-approval from your bank or credit union, then let the dealership compete with it. Whichever is cheaper wins, and you will know which is which in an afternoon.
Start with a number, not a guess
The riders who have the best buying experience are the ones who walked in already knowing what they qualified for. It takes very little time and it changes the entire conversation.
Start here, get a trade value, or call us at (337) 289-3030 and ask for the finance office. We are at 724 I-10 South Frontage Rd, Scott, LA 70583, and we work with buyers across Lafayette, Lake Charles, Baton Rouge, Houma, and New Orleans.
This article explains how motorcycle financing works generally. It is not financial advice, and it does not constitute an offer of credit. Terms, rates, and program availability change. Talk to our finance office for current options.